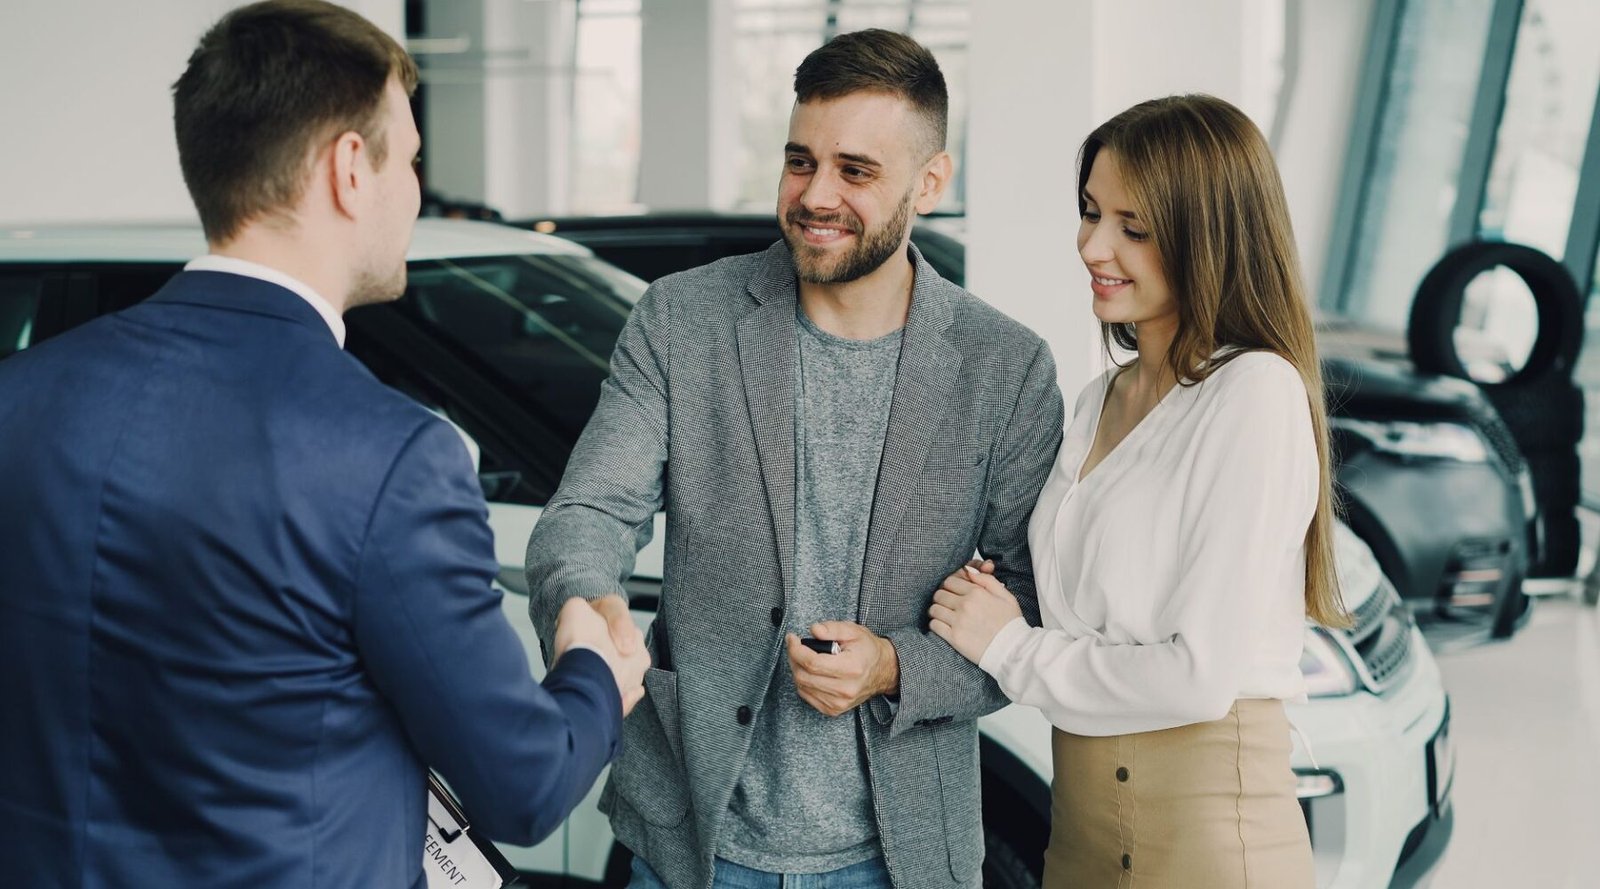
Financing a car is a significant decision that requires careful consideration. Whether you are purchasing a new vehicle or a used one, understanding the intricacies of car financing can help you make informed choices and save money in the long run. In this article, we will explore the key factors to keep in mind before financing a car.
Understanding your credit score
Your credit score is one of the most critical factors in determining your financing options. Lenders use this score to assess your creditworthiness, which directly impacts the interest rate you may receive. A higher score generally translates to lower interest rates, which can save you thousands over the life of the loan.
Before applying for financing, check your credit report for inaccuracies and take steps to improve your score if necessary. Paying down existing debt, making timely payments, and avoiding new inquiries can help boost your score. Consider obtaining a copy of your credit report from one of the major credit bureaus—Equifax, Experian, or TransUnion—before you start shopping for a car.
Types of financing options
When it comes to financing a car, there are several options available, each with its pros and cons. The most common methods include:
- Dealer financing: Many dealerships offer financing through their own lenders. While this can be convenient, it’s essential to compare the terms with other options, as dealer financing may come with higher interest rates.
- Bank or credit union financing: Traditional banks and credit unions often provide competitive rates for auto loans. Establishing a relationship with a local credit union can be beneficial, as they may offer lower rates and more personalized service.
- Online lenders: Numerous online platforms provide car loans with varying terms. These lenders can often offer quick approvals and competitive rates, making them a viable option for tech-savvy buyers.
Loan terms and conditions
The terms of your auto loan can significantly impact your overall cost. Common terms include:
- Loan length: Auto loans typically range from 36 to 72 months. While longer loans may lower your monthly payment, they can increase the total interest paid over the life of the loan.
- Interest rates: The interest rate on your loan will depend on your credit score, the lender, and the loan term. Always shop around to compare rates and terms from multiple lenders.
- Down payment: A larger down payment can reduce your loan balance and lower your monthly payment. Aim for at least 20 percent of the car’s purchase price to avoid being upside down on your loan.
Loan pre-approval advantages
Getting pre-approved for a loan before you start shopping for a car can provide several advantages. First, it gives you a clear idea of your budget and what you can realistically afford. Additionally, having pre-approval can give you leverage when negotiating with dealers, as it shows you are a serious buyer with financing already secured.
To obtain pre-approval, you will need to provide some basic financial information to the lender, including your income, employment status, and any existing debts. The lender will then review your credit profile and provide you with a pre-approval letter outlining the loan amount, interest rate, and terms.
Understanding total cost of ownership
When financing a car, it’s essential to consider the total cost of ownership, which encompasses more than just the monthly payment. This includes:
- Insurance: Auto insurance rates can vary significantly based on the vehicle and your driving history. Be sure to factor in these costs when budgeting for your new car.
- Maintenance and repairs: Different vehicles have varying costs for maintenance and repairs. Research your prospective car’s reliability and typical repair costs before making a purchase.
- Fuel efficiency: Consider the fuel economy of the vehicle, as this will impact your ongoing expenses. A more fuel-efficient car can save you money over time.
- Depreciation: Some vehicles hold their value better than others. Understanding the expected depreciation of the car you choose can help you make a more informed financial decision.
Financing a car is not just about choosing the right vehicle; it is also about understanding the financial implications of your purchase.
The role of credit scores in financing a car
When financing a car, your credit score can significantly influence the interest rates you receive, the total cost of the loan, and even your eligibility for certain financing options. Understanding how credit scores work and what factors influence them can empower you to make informed decisions before stepping into a dealership.
Credit scores typically range from 300 to 850, with higher scores indicating better creditworthiness. Lenders use these scores to assess the risk of lending money. A score above 700 is generally considered good, while scores below 600 may lead to higher interest rates or even loan denial. For example, a borrower with a score of 760 may secure a loan at 3% interest, while someone with a score of 580 may be looking at rates upwards of 10%.
Several factors influence your credit score, including payment history, credit utilization, length of credit history, types of credit in use, and recent credit inquiries. For instance, consistently making on-time payments is crucial, as late payments can stay on your credit report for up to seven years, dragging down your score. Similarly, maintaining a low credit utilization ratio—ideally below 30% of your available credit—can positively affect your score.
Before financing, it’s wise to check your credit score. Many financial institutions offer free credit score checks, and this will help you identify any areas for improvement. If your score is lower than desired, you may consider taking steps to boost it, such as paying off outstanding debts, disputing inaccuracies on your credit report, or avoiding taking on new credit in the months leading up to your car purchase.
“Understanding your credit score is not just about getting a loan; it’s about saving money over the life of that loan.”
Moreover, it’s crucial to understand the difference between soft and hard inquiries on your credit report. A soft inquiry occurs when you check your own credit or a lender pre-approves you for a loan without impacting your score. However, a hard inquiry happens when you formally apply for credit, which can cause a slight dip in your score. If you are shopping around for the best rates, it is advisable to do so within a short time frame (typically 14 to 45 days), as multiple hard inquiries during this period are often treated as a single inquiry by scoring models.
Finally, many dealerships and financing companies offer pre-approval options, which can be particularly beneficial. Pre-approval allows you to gauge your potential interest rate and loan amount before negotiating terms. This process not only provides clarity on what you can afford but also strengthens your negotiating position at the dealership, as it shows you are a serious buyer with financing already lined up.
In summary, a solid understanding of how your credit score impacts your financing options can lead to better rates, lower monthly payments, and overall savings on your car purchase. By proactively managing your credit health before you start shopping, you position yourself to secure the best possible financing deal.
Understanding the total cost of ownership
When financing a car, most buyers focus primarily on monthly payments and interest rates. However, it’s crucial to understand the total cost of ownership (TCO), which encompasses not just the purchase price but also a variety of other expenses that can add up significantly over time.
The total cost of ownership includes factors like insurance, fuel, maintenance, and depreciation. Let’s break down each of these components to help you get a more accurate picture of what financing a car will truly cost you.
Insurance: The make and model of the car significantly influence insurance premiums. For example, a new luxury sedan might cost substantially more to insure than a compact hatchback. Before making a purchase, it’s wise to get insurance quotes for the specific vehicles you’re considering. Websites like Geico or Progressive offer quote tools that can help you compare rates based on the car’s details.
Fuel Efficiency: Fuel costs can greatly impact your budget, especially if you drive long distances. According to the U.S. Department of Energy, a car that gets 30 miles per gallon (MPG) will cost significantly less in fuel than one that gets 15 MPG, assuming a similar driving distance. Calculating your commute and considering the car’s MPG will give you a clearer understanding of your ongoing expenses.
Maintenance and Repairs: Different vehicles have varying maintenance costs. Luxury brands often have higher repair costs due to specialized parts and service. For instance, a Toyota Corolla may have lower long-term maintenance costs compared to a BMW 3 Series. Researching average maintenance costs for the car models you’re considering can help you avoid unexpected expenses down the line. Websites like Edmunds and Consumer Reports provide insights into the long-term reliability and maintenance costs of various vehicles.
Depreciation: This is one of the most significant factors affecting the total cost of ownership. New cars can lose 20% to 30% of their value in the first year alone. Understanding the depreciation rate of the vehicle you want to finance can help you make a more informed decision. Some brands, like Honda and Subaru, tend to hold their value better than others. Platforms like Kelley Blue Book can help you analyze the resale value of different makes and models.
To truly assess the total cost of ownership, consider creating a spreadsheet that outlines all these factors over a typical ownership period, say five years. By including your estimated monthly payments along with projected insurance, fuel, maintenance, and depreciation, you can see the full financial impact of your decision.
In conclusion, while it’s easy to get caught up in the allure of financing a car with low monthly payments, a comprehensive understanding of the total cost of ownership will empower you to make a more financially sound decision. Remember that the goal is not just to afford the car today but to consider how it fits into your long-term financial picture.
“Financing a car is not just about the loan terms; it’s about understanding the entire financial commitment.”
Understanding the total cost of ownership
When financing a car, it’s crucial to look beyond the monthly payment and assess the total cost of ownership (TCO). This includes not just the vehicle’s price but also factors like insurance, maintenance, fuel, and depreciation. Evaluating these components can substantially change your financial picture.
Start with insurance. Rates can vary widely based on the make and model of the car, your driving history, and your location. For example, a new sports car might have significantly higher insurance premiums than a reliable sedan. It’s essential to get insurance quotes before finalizing your purchase. This will give you a clearer picture of your overall monthly expenses.
Next, consider maintenance costs. Some vehicles are more reliable than others, and repair costs can differ dramatically between brands. For instance, luxury brands often carry higher maintenance and repair expenses. Tools like the Edmunds maintenance cost calculator can help you estimate these expenses based on the vehicle you’re considering.
Fuel efficiency is another vital aspect of TCO. The difference between a fuel-efficient car and a gas guzzler can amount to thousands of dollars over the life of the vehicle. Look for vehicles with good gas mileage ratings and consider fuel type; for example, hybrid and electric vehicles generally offer lower operating costs compared to traditional gas-powered cars.
Depreciation is often the most overlooked cost in TCO calculations. Cars lose value quickly, with many models depreciating by 20% or more within the first year. Research the depreciation rates of the vehicles you are considering. Brands like Toyota and Honda tend to hold their value better than luxury brands, which may depreciate faster.
“Understanding the total cost of ownership will help you make a more informed decision that aligns with your financial situation and long-term goals.”
Additionally, don’t forget to factor in any potential taxes or fees that may apply when purchasing a vehicle. Sales tax, registration fees, and title transfer costs can add up quickly and should be included in your financing discussions.
Lastly, if you’re financing through a dealer, ask about any hidden fees or add-ons that might inflate the total cost of the loan. It’s worth taking the time to read all the fine print and understand what you’re agreeing to. By evaluating these factors, you can avoid surprises and ensure that you’re making a sound financial decision.
Related reading: Buying a Certified Pre-Owned Car: The Complete Checklist, and The best trucks for camping and overlanding. For an outside reference on this topic, see Consumer Reports' car-buying advice.
1 Response