Negotiating the price of a new car can be a daunting task for many buyers. However, understanding the process and employing effective strategies can significantly enhance your chances of securing a favorable deal. This guide will provide you with the necessary tools to navigate the negotiation landscape with confidence.
Research the vehicle’s market value
Before entering negotiations, it is crucial to know the market value of the vehicle you intend to purchase. Utilize resources such as Kelley Blue Book, Edmunds, and NADA Guides to assess the fair market price based on the car’s make, model, year, and condition. These platforms provide comprehensive insights into local pricing trends and can help you establish a baseline for negotiations.
Understand dealership tactics
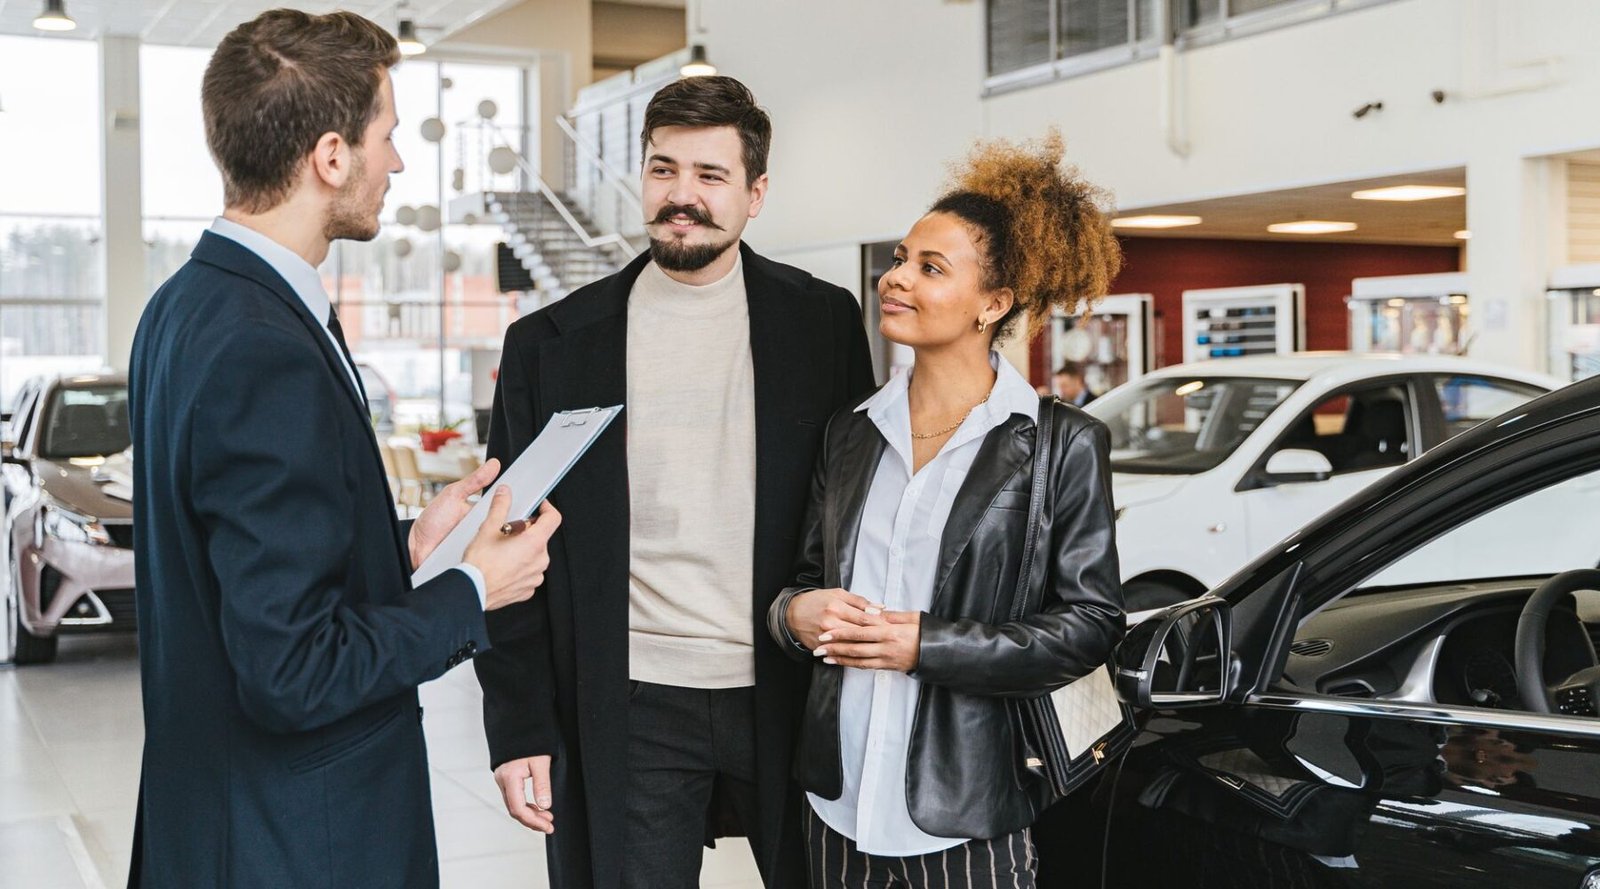
Dealerships employ various tactics to maximize their profits during negotiations. Common strategies include presenting the vehicle’s price in a way that emphasizes the monthly payment rather than the total cost. This can lead buyers to overlook the final price and focus solely on what they can afford monthly. Be aware of such tactics and maintain focus on the overall cost of the vehicle.
Know your financing options
Understanding your financing options can significantly impact your negotiation ability. Research loan rates from banks, credit unions, and online lenders before visiting the dealership. Pre-approval for a loan can provide you with a clear budget and leverage during negotiations. Knowing your financing terms also allows you to gauge the dealer’s financing offer and compare it effectively.
Timing your purchase
The timing of your car purchase can influence the negotiation process. Dealerships often have monthly, quarterly, and annual sales goals, making the end of these periods an opportune time for buyers. Additionally, shopping during holiday sales events or at the end of the model year can result in more significant discounts as dealerships look to clear inventory. Being strategic about when you shop can give you an advantage.
Be prepared to walk away
One of the strongest negotiating tools a buyer has is the willingness to walk away. If the dealer is not meeting your expectations, express your dissatisfaction and be prepared to leave. This action can sometimes prompt the salesperson to make a better offer or provide additional incentives to keep you from leaving the dealership. Remember, there are plenty of other dealerships and vehicles available, so don’t feel pressured to settle for a deal that doesn’t meet your needs.
Negotiate trade-in values separately
If you are trading in your old vehicle, negotiate its value separately from the new car price. Dealers may attempt to combine these negotiations to confuse you or to obscure the final deal. Start by researching your trade-in’s value to establish a fair price. Once you have agreed on the cost of the new car, turn your attention to the trade-in value to ensure you get the best overall deal.
Negotiating the price of a new car requires preparation, knowledge, and confidence. By arming yourself with market research, understanding dealership tactics, exploring financing options, timing your purchase strategically, being willing to walk away, and negotiating trade-in values separately, you can maximize your chances of securing the best deal possible. Approach the process with a clear strategy, and you will find yourself in a much stronger position during negotiations.
Understanding dealership financing tactics
One of the most critical aspects of negotiating the price of a new car involves understanding how dealerships leverage financing to influence pricing. Many buyers focus solely on the sticker price of the vehicle, but it’s essential to consider how the total cost of financing can affect your overall deal. Dealerships often present financing options that seem attractive on the surface but may not be the best choice in the long run.
When you enter a dealership, salespeople may steer conversations towards monthly payment figures rather than the total price of the car. This tactic can lead you to agree to a higher car price if the monthly payment appears manageable. For instance, a dealership might offer a five-year loan at a low-interest rate on a more expensive vehicle, making it seem more appealing. However, this could result in paying significantly more in interest over the loan’s life than if you had negotiated a lower price on a less expensive vehicle.
“Always negotiate the total price of the car rather than focusing solely on the monthly payment.”
To effectively navigate this, start by securing your financing options before visiting the dealership. Obtain pre-approval for a loan from your bank or credit union. This gives you a concrete idea of what you can afford and allows you to compare dealership financing offers against your pre-approved rate. If the dealership offers a lower rate, ensure to scrutinize the terms and consider how they compare against your pre-approved loan.
Additionally, be aware of the dealer markup on financing. Some dealerships may inflate interest rates offered through their financing departments. The difference between the rate your bank offers and what the dealer is proposing can be substantial. For example, if your bank offers a 3% interest rate and the dealer presents 5%, negotiating down to a rate closer to your bank’s can save you hundreds or even thousands over the life of the loan.
Another financing tactic involves the use of add-ons and extras that can inflate the overall cost of the vehicle. Dealers often try to sell add-ons like extended warranties, gap insurance, or additional features that may seem beneficial but often come at a hefty premium. Before agreeing to these extras, assess their true value. If you are interested in an extended warranty, for instance, research third-party options that may be more cost-effective.
“Don’t let the dealer pressure you into add-ons that you don’t need; assess their value independently.”
While negotiating, it’s also beneficial to have a clear understanding of your credit score and how it can impact financing offers. A higher credit score generally qualifies you for better rates. If your credit score isn’t where you want it to be, consider postponing your purchase to improve it, as better rates will significantly reduce your total cost.
Finally, be prepared to walk away. If the terms being offered are not satisfactory, don’t hesitate to leave. This sends a strong signal to the dealership that you are serious about getting a fair deal. Oftentimes, this can lead to a better offer once they realize you are not willing to settle for less.
By understanding these financing tactics and being proactive in securing the best loan terms, you can negotiate not only the price of the car but also the overall cost of your vehicle purchase more effectively.
Understanding dealership financing tactics
When negotiating the price of a new car, it’s essential to grasp the various financing tactics that dealerships employ. Many buyers focus solely on the sticker price, overlooking how financing can affect the total cost of the vehicle. Understanding these tactics will empower you to negotiate more effectively.
Dealerships often use financing as a way to enhance their profits, sometimes overshadowing the vehicle’s price itself. For instance, they may offer low monthly payments that can seem enticing, but these often come at the cost of a higher overall price for the car or a longer loan term. This can lead to you paying significantly more in interest over time. Always calculate the total cost of financing, including interest rates and loan duration, rather than fixating on the monthly payment.
“A good negotiator understands that the deal is not just about the price but also about how the financing terms play into that price.”
Another tactic to be aware of is the dealer markup on interest rates. Lenders often provide dealerships with a base interest rate that they can mark up when offering financing to customers. A dealer might present you with a rate higher than what you could secure on your own. If you have pre-approval from a bank or credit union, you can leverage this information during negotiations. Presenting a lower interest rate from another lender can compel the dealer to match or beat that rate to close the deal.
Moreover, the timing of your purchase can strategically enhance your negotiating power. Dealerships have monthly and quarterly sales targets. If you visit toward the end of the month or quarter, salespeople may be more eager to negotiate to meet their goals. Additionally, consider shopping during holiday sales events, as dealerships often provide incentives that can lead to better financing options.
“Timing your purchase can be just as crucial as how you negotiate. Use the dealer’s need to meet quotas to your advantage.”
A critical aspect of negotiation is the trade-in value of your current vehicle. Many buyers are unaware that the trade-in value can be used as a bargaining chip. Research your car’s worth beforehand using online appraisal tools. When discussing the new vehicle, frame your trade-in as part of the overall deal rather than a separate transaction. This approach can help you negotiate a better price for the new car while maximizing the value of your trade-in.
Lastly, approach the negotiation with a mindset of collaboration rather than confrontation. Building rapport with the salesperson can lead to more favorable terms. Be polite but firm about your budget and expectations. If the salesperson senses that you are genuinely interested but have a strict limit, they may be more inclined to work with you to achieve a mutually beneficial agreement.
“Negotiation is about finding a win-win situation. Building a relationship can often yield better results than a purely transactional interaction.”
In summary, understanding dealership financing tactics, being aware of the timing of your purchase, leveraging your trade-in, and fostering a collaborative relationship with the salesperson can significantly enhance your negotiating power when purchasing a new car. By taking these factors into account, you can ensure that you are not only getting a fair price but also securing favorable financing that aligns with your financial goals.
Understanding dealership financing tactics
When negotiating the price of a new car, understanding the financing options the dealership offers can significantly impact your final deal. Dealerships often present financing as a convenience, but it can also serve as a critical negotiation leverage point. Here’s how to navigate this aspect effectively.
First, it’s essential to know that dealerships typically make a profit through both the sale of the vehicle and the financing arrangements they offer. This means that if you can negotiate the price of the car down, the dealership may try to recoup that loss by steering you towards a higher interest rate or unfavorable loan terms. To counter this, always come prepared with your own financing options. Secure pre-approval from your bank or credit union before setting foot in the dealership. This not only provides you with a clear budget but also gives you a benchmark against which to measure the dealership’s financing offers.
For example, suppose you are approved for a loan with a 3.5% interest rate at your local bank. When you approach the dealership, they might initially present a financing deal at 4.5%. In this scenario, you can use your pre-approval as leverage to negotiate a better rate. By showing them your better offer, you can potentially lower their interest rate or negotiate other terms that make the deal more favorable.
“Your leverage increases when you have a pre-approved financing offer in hand. Don’t shy away from using it to negotiate better terms.”
Additionally, be aware of the total cost of the loan rather than just the monthly payments. Dealerships often advertise low monthly payments to attract buyers, but this can be misleading if the loan term is extended significantly. Calculate the total interest paid over the life of the loan to ensure you’re not being lured into a long-term deal that ultimately costs more. A loan with a lower monthly payment could mean a longer term, which might result in higher interest payments overall.
Another tactic employed by dealerships is to bundle add-ons, such as extended warranties or service packages, into the financing. This can inflate your loan amount significantly. Always assess these add-ons individually. If they are beneficial, consider paying for them upfront rather than rolling them into your loan. This reduces the total amount financed and ultimately saves you money on interest.
Moreover, timing your purchase can also influence your financing options. End-of-month or end-of-year sales often lead dealerships to offer better deals to meet sales quotas. During these times, they may be more willing to negotiate not just on the car price but also on financing terms. Keeping an eye on these cycles can provide additional opportunities to secure a better deal.
“Timing your purchase can play a significant role in the negotiation process. Use seasonal sales to your advantage for better financing options.”
Finally, be prepared to walk away if the financing terms do not meet your expectations. A dealership may initially resist lowering their rates, but demonstrating that you are willing to walk away can prompt them to reconsider. Always remember that the goal is to find a deal that works for you, not just the dealership.
In summary, understanding the interplay between car pricing and financing options is vital for successful negotiation. By doing your homework, securing pre-approval, and being aware of the dealership’s tactics, you can navigate the financing landscape effectively and achieve a better overall deal on your new car.
Related reading: The best midsize pickup trucks on the market today, and The best three-row SUVs for large families balancing space, safety, and value. For an outside reference on this topic, see Consumer Reports' car-buying advice.